Advertiser disclosure: This Chime Credit Builder review may contain partner links. Safe Mobile Banking may earn a fee if you sign up, at no cost to you. It never changes a Safe Mobile Banking Score. How we make money.
Short answer
Is Chime Credit Builder safe and worth it? Chime Credit Builder is now called Chime Card. It’s a secured charge card offered through Stride Bank, N.A. or The Bancorp Bank, N.A., both FDIC member banks. It has no annual fee, no interest and no credit check, and Chime reports it to all three credit bureaus. You must open a Chime Checking Account, pay the full balance each month, and the money you move in becomes your spending limit.
See Chime Card’s current terms (No annual fee or interest. Requires a Chime Checking Account.)
Last verified: November 17, 2026.
Chime Credit Builder at a glance
| Item | What Chime’s terms say | Source |
|---|---|---|
| Current name | Chime Card (“the next generation of Credit Builder”) | Chime |
| Card type | Secured charge card, paid in full every month | Card agreement |
| Annual fee, interest | $0 annual fee, no interest rate, no minimum payment | Card agreement |
| Late fee | None, but a late payment puts the account in default | Card agreement |
| Other fees | $2.50 out-of-network ATM, $2.50 over-the-counter advance, $20 expedited card, up to $50 metal card | Card agreement |
| Credit check | None to apply | Chime |
| Deposit | No minimum; your limit generally equals what you move in | Card agreement |
| Bureaus | TransUnion, Experian and Equifax | Chime |
| Bank | Stride Bank, N.A. or The Bancorp Bank, N.A., Members FDIC | Chime |
| App Store rating | 4.8 from about 1.66 million ratings | App Store |
What happened to Chime Credit Builder?
Chime renamed it. Chime’s credit-builder page now says “Credit Builder is now Chime Card” and calls Chime Card “the next generation of Credit Builder.” Chime announced the new card on September 9, 2025, and said current Credit Builder cardholders could upgrade in the app.
Chime Card keeps the credit-building setup and adds cash back for members who get qualifying direct deposits. Chime’s page also warns that once you switch to Chime Card, you can’t switch back to Credit Builder.
How does Chime Credit Builder work?
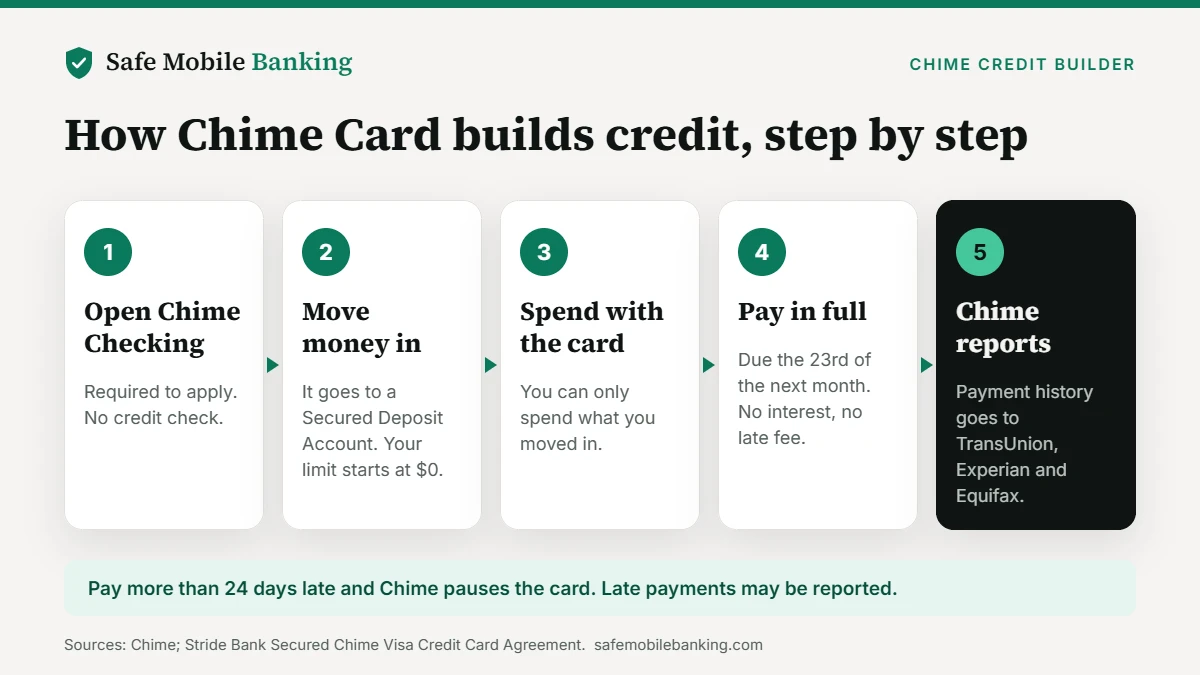
Chime Card works like a prepaid limit with a credit card’s reporting. Here is the flow, step by step, from Chime’s terms:
- Open a Chime Checking Account. Chime says you must open one to apply. There’s no credit check.
- Move money in. Money you add goes into a Secured Deposit Account held by the bank. Your starting limit is $0, and your limit generally equals what sits in that account.
- Spend with the card. You can’t spend more than you moved in.
- Pay the statement in full. Statements arrive by the 28th and are due on the 23rd of the next month. You can pay from the secured money. An optional feature, Safer Credit Building, can pay it for you.
- Chime reports to the bureaus. Chime reports payment amount, payment date and highest balance to TransUnion, Experian and Equifax. It says utilization isn’t reported.
Because utilization isn’t reported, a large purchase shouldn’t show up as a high balance against your limit. Your payment history still does, so a missed payment can hurt.
What does Chime Card cost?
The core card is free. The Stride Bank card agreement says there is no annual fee, no interest rate and no foreign transaction fee. The fees that do exist are for extras:
- $2.50 per out-of-network ATM withdrawal (Allpoint and some other ATMs are free).
- $2.50 per over-the-counter cash advance.
- $20 for an expedited replacement card.
- Up to $50 plus sales tax for a metal card. A plastic replacement is free.
The Secured Deposit Account pays no interest. Money you park there to raise your limit earns nothing.
What happens if you pay late?
There’s no late fee, but a late payment still counts. The card agreement says an unpaid balance after the due date is late and puts you “in Default.” Chime’s page says that if you don’t pay within 24 days of the due date, the card is paused until you pay in full, and late payments may show up on your credit report.
The agreement also says the bank can act against your secured deposit after a default, and that you “could lose all funds in your Secured Deposit Account” if you don’t repay. Set up autopay if you can.
Does Chime Credit Builder raise your credit score?
It can help, but nothing is promised. Chime cites a September 2025 Experian study of members whose first Credit Builder purchase was between April and August 2024. The top 10% saw their FICO Score 8 rise 71 points after about 8 months. The average gain across everyone in the study was 28 points. Chime says improvement isn’t guaranteed and other credit activity affects results.
Your result depends on your full credit file. A card that reports on-time payments adds positive history. It doesn’t erase late payments or collections elsewhere.
Is Chime Credit Builder safe?
Your money sits at a bank, but with conditions. Chime says it’s “a financial technology company, not a bank,” and that Chime itself isn’t FDIC-insured. Banking services, including the card, come from Stride Bank, N.A. or The Bancorp Bank, N.A.; Chime says the back of your card names your issuer. Both appear as active banks in FDIC BankFind (certificates 4091 and 35444).
The secured deposit agreement says the money is held in a pooled account and that “certain conditions must be satisfied for pass-through deposit insurance coverage to apply.” Coverage is up to $250,000 per depositor, per insured bank, per ownership category. Stride can also, at its discretion, require seven days’ notice before you withdraw secured money, and you can’t take it out while you owe a balance.
On security, Chime says members can use Face ID, fingerprint and two-factor login, block the card instantly in the app and turn on instant transaction alerts. Chime cards carry Visa’s Zero Liability Policy, which requires you to report unauthorized use right away.
What do complaints filed with the federal consumer bureau show?
The Consumer Financial Protection Bureau’s database lists 12,352 complaints about Chime Financial Inc received from November 17, 2025 to November 17, 2026. Most concern its checking and savings accounts (8,348). Complaints filed under the credit card product numbered 1,164. The most common credit card issue consumers chose was “Problem with a purchase shown on your statement” (755).
Across all products, consumers most often picked “Managing an account” (4,529). Chime responded on time to 12,351 of the 12,352. Chime reported closing 663 with monetary relief. Chime is a large company, and the bureau notes that companies with more customers may get more complaints. See how Chime compares with 25 other money-app companies in our Money App Complaint Report 2026.
In May 2024, the CFPB issued a consent order against Chime Financial. The bureau found Chime didn’t refund closed-account balances within its promised 14 days in thousands of cases. The order required a $3.25 million penalty and at least $1.3 million in refunds to consumers. Chime agreed to the order.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
Chime Credit Builder Safe Mobile Banking Score: 7.5/10
| Test | Points | Why |
|---|---|---|
| Deposit and license protection | 3 / 3 | Offered through Stride Bank, N.A. or The Bancorp Bank, N.A.; secured money held by named FDIC member banks, both found in FDIC BankFind. Pass-through conditions apply. |
| Fee transparency | 2 / 2 | Every fee is in the public card agreement. |
| Regulatory record | 0 / 2 | A CFPB consent order (May 2024) falls inside the last three years. |
| Security features | 1.5 / 2 | Two-factor login is available, but Chime doesn’t say it’s on by default (0.5); card block, instant alerts and biometric login (1). |
| User ratings | 1 / 1 | 4.8 on the App Store from about 1.66 million ratings. |
Who is Chime Credit Builder good for?
Good fit
- You want to build payment history without a credit check or interest.
- You already bank with Chime, or you’re fine opening Chime Checking.
- You can pay the full statement every month, or let autopay do it.
Skip it if
- You don’t want a Chime Checking Account.
- You want your money to earn interest while it secures the card.
- You need a revolving line you can carry month to month.
Compare it with other options in our guides to credit builder cards and credit builder loans, or read our Kikoff review. See how we rate every app.
See Chime Card’s current terms (No annual fee or interest. Requires a Chime Checking Account.)
How Chime Card scored, test by test
Each test follows the written rules on how points are awarded.
| Test | Points | Why |
|---|---|---|
| Deposit and license protection | 3 / 3 | The card is offered through Stride Bank, N.A. or The Bancorp Bank, N.A., both Members FDIC, and it works with a Chime Checking Account. |
| Fee transparency | 2 / 2 | No annual fee, no interest and no credit check are stated on Chime’s own credit-builder page and card terms. |
| Regulatory record | 0 / 2 | In May 2024, the CFPB issued a consent order against Chime Financial over slow refunds of closed-account balances. That is inside the three-year window. |
| Security features | 1.5 / 2 | Chime says members can use two-factor login, but doesn’t state it is on for every account (0.5). We confirmed instant card blocking, transaction alerts and Face ID or fingerprint login (1). |
| User ratings | 1 / 1 | 4.8 on the App Store from about 1.66 million ratings. |
Chime Credit Builder FAQ
Is Chime Credit Builder a credit card?
Yes, in a specific way. Chime Card, the new name for Credit Builder, is a secured charge card from Chime’s partner banks. You spend money you’ve moved into a secured account and must pay the full balance every month. There’s no interest rate and no minimum payment, and Chime reports it to TransUnion, Experian and Equifax.
Does Chime Credit Builder do a credit check?
No. Chime says there’s no credit check to apply. You do need to open a Chime Checking Account first, and you need to move money into the Secured Deposit Account before you can spend, because your starting limit is $0 and your limit generally equals the amount you’ve added.
Why do I owe Chime Credit Builder money?
Each statement shows what you spent during the month, and the full amount is due on the 23rd of the next month. You can pay it from the secured money or turn on Safer Credit Building. If you don’t pay within 24 days of the due date, Chime pauses the card, and late payments may be reported.
Does Chime Credit Builder report utilization?
No. Chime says utilization isn’t reported for Chime Card. It reports payment amount, payment date and highest balance to the three bureaus. That means a big purchase shouldn’t look like a maxed-out card, but a missed payment can still hurt your credit history.
Can you get your deposit back from Chime Card?
You can withdraw secured money up to your available amount once your balance is paid. The secured account agreement says Stride Bank may, at its discretion, require seven days’ notice, and you can’t withdraw while you still owe on the card. If you default, the bank can use the deposit to cover what you owe.
Is Chime Card FDIC insured?
Chime itself isn’t a bank and isn’t FDIC-insured. Your money is held by Stride Bank, N.A. or The Bancorp Bank, N.A., both FDIC members. The secured account agreement says certain conditions must be met for pass-through insurance to apply, up to $250,000 per depositor, per insured bank, per ownership category.
Sources
- Chime: Chime Card (formerly Credit Builder)
- Chime: How Chime Card works
- Stride Bank: Secured Chime Visa Credit Card Agreement (Rev. 02/2026)
- Stride Bank: Application Disclosure and Secured Account Agreement
- Chime press release, September 9, 2025 (Business Wire)
- Chime: Safety and security
- CFPB: Chime Financial, Inc. enforcement action
- CFPB Consumer Complaint Database
- FDIC BankFind
- Apple App Store: Chime – Mobile Banking
This review is information, not financial advice. Check Chime’s current terms before you apply.