Facebook Marketplace Scams: 5 Payment Tricks and How to Avoid Them
The fake Zelle upgrade, the verification-code trick, overpayments and off-checkout deposits: how Facebook Marketplace scams work and 3 rules to avoid them.
Independent safety reviews
Safe mobile banking starts with the facts. Our research software checks each company’s fees, terms, federal complaints and app ratings, then scores each full review on the same Safe Mobile Banking Score.
Data we check for every review
New reviews publish every week. Each one answers whether the app is safe, what it really costs and who should skip it.

The fake Zelle upgrade, the verification-code trick, overpayments and off-checkout deposits: how Facebook Marketplace scams work and 3 rules to avoid them.

If your bank account was hacked, call your bank now. Federal rules cap your loss at $50 if you report within two business days. Here are the first 3 steps.
Greenlight lets parents control where kids spend, get alerts and lock the card, with FDIC-insured funds. Here’s what it costs and 3 settings to turn on.
Experian Boost is free and can add on-time bills to your Experian file, but only lenders that check Experian will see it. Here’s what to check first.
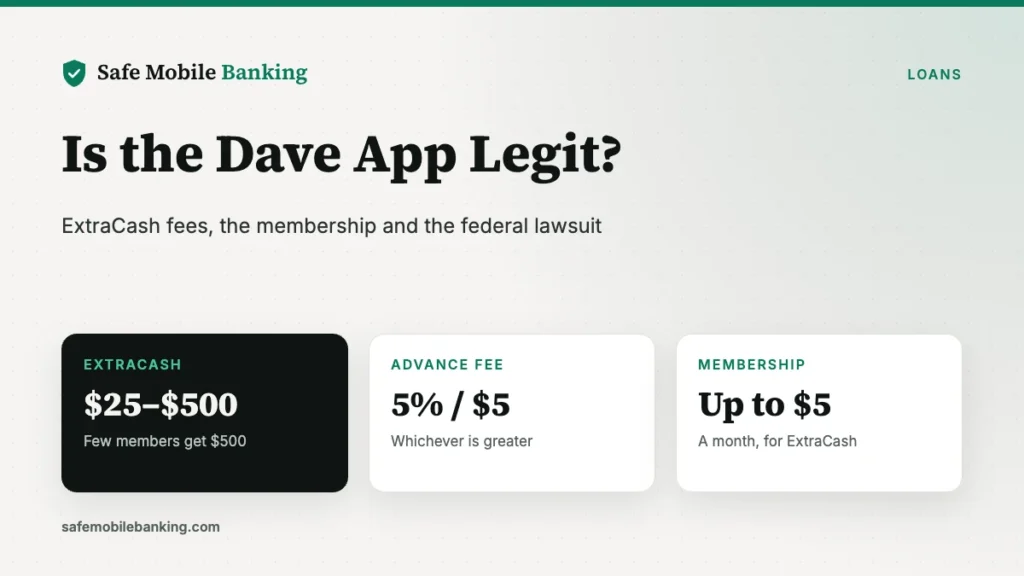
Dave is a real public company, but ExtraCash costs $5 or 5% per advance plus up to $5 a month, and the Justice Department is suing over its fees.
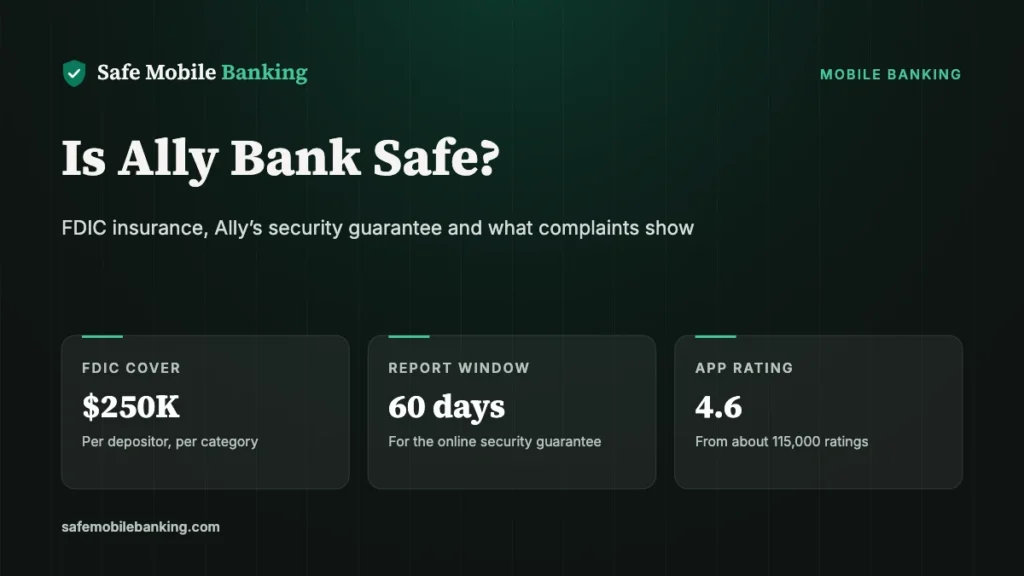
Ally Bank is FDIC insured and guarantees unauthorized online transactions you report within 60 days. Here’s what complaints show and 3 habits to keep it safe.
The Safe Mobile Banking Score
Every scored app is measured on the same five tests, worth 10 points in total. 10 is the safest. Each scored review shows where every point came from, with links to the sources. The score is our opinion, based on those public facts.
Some companies pay us when you open an account through our links. That money never changes a Safe Mobile Banking Score, a complaint count or what we write. Reviews are researched and written by AI-assisted software designed by M. Curtis McCoy, using each company’s own pages and public records like the Consumer Financial Protection Bureau complaint database, and every number is re-checked against its source before publishing.
Read the review first. It takes five minutes and shows the costs and complaints the sign-up page leaves out.
Site design and search strategy by M. Curtis McCoy.