Advertiser disclosure: Is Experian Boost safe? We answer that independently. Safe Mobile Banking may earn a commission from some companies we review, but we don’t earn anything from Experian, and commissions never change what we say. How we make money.
Short answer
Is Experian Boost safe? Yes. It’s a free tool from Experian, one of the three credit bureaus, that adds on-time bills like phone, utilities and streaming to your Experian file. Experian says the average gain is 13 points on FICO Score 8. The limits: it only changes your Experian file, and lenders that check Equifax or TransUnion won’t see it.
- Free, and you can remove accounts at any time
- Counts bills that normally don’t build credit
- Only affects Experian data; some scores stay flat or drop
See 3 checks before you connect your bank (Free. Takes one minute.)
Last verified: November 15, 2026, against Experian’s Boost page, the Consumer Financial Protection Bureau’s Experian case and complaint database, and the Apple App Store.
Is Experian Boost safe? The short version
| Question | Answer | Source |
|---|---|---|
| Who runs it? | Experian, one of the three national credit bureaus | Experian |
| Cost | Free | Experian |
| Average gain | 13 points on FICO Score 8, for people who see an increase; results vary | Experian |
| Which credit file? | Experian only, not Equifax or TransUnion | Experian |
| Can I undo it? | Yes. Remove added accounts at any time | Experian |
| Regulator action against Experian | CFPB lawsuit over dispute handling (January 2025), ongoing | CFPB |
How does Experian Boost work?
You connect the bank accounts you use to pay bills. Experian looks for on-time payments to eligible companies and adds them to your Experian credit file. Experian says most people who get an increase see an average of 13 points on their FICO Score 8, though results vary and some scores stay the same or go down.
Bills that count include mobile and landline phone; electricity, gas, water and trash; cable, satellite and internet; video streaming like Netflix, Disney+, HBO and Hulu; and home, auto and life insurance. Rent counts only if you pay online to select property managers or rent platforms. Health insurance, and rent paid by check, cash, PayPal, Venmo or Zelle, don’t count.
Is it safe to connect your bank to Experian Boost?
Experian says your information remains private and uses bank-level SSL encryption. Keep in mind what you’re sharing: Boost reads your bank transactions to find bill payments, so you’re giving a credit bureau a view of your spending.
You stay in control. Experian says you can remove accounts you’ve added at any time, and if your score dropped, it should return to its previous result after you disconnect.
Will lenders see your Experian Boost?
Only some. Boost changes your Experian credit file, and Experian calculates the boost on FICO Score 8. Lenders that pull your Equifax or TransUnion report, or use a different score model, won’t see it, and Experian notes that not all lenders use Experian credit files. Boost helps most with thin credit files and with lenders you know check Experian.
What do Experian’s complaint records show?
Experian is one of the most complained-about companies in the federal database, but almost all of it is about credit reports, not Boost. The Consumer Financial Protection Bureau logged 2,069,959 complaints against Experian Information Solutions Inc. from November 15, 2025 to November 15, 2026. The top issues were incorrect information on a report (1,251,027), problems with Experian’s investigation (401,167) and improper use of a report (394,719).
The bureau also sued Experian in January 2025, alleging it ran “sham investigations” of credit report disputes. Experian called the case without merit, and the allegations haven’t been proven in court. As of January 2026, discovery was ongoing.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
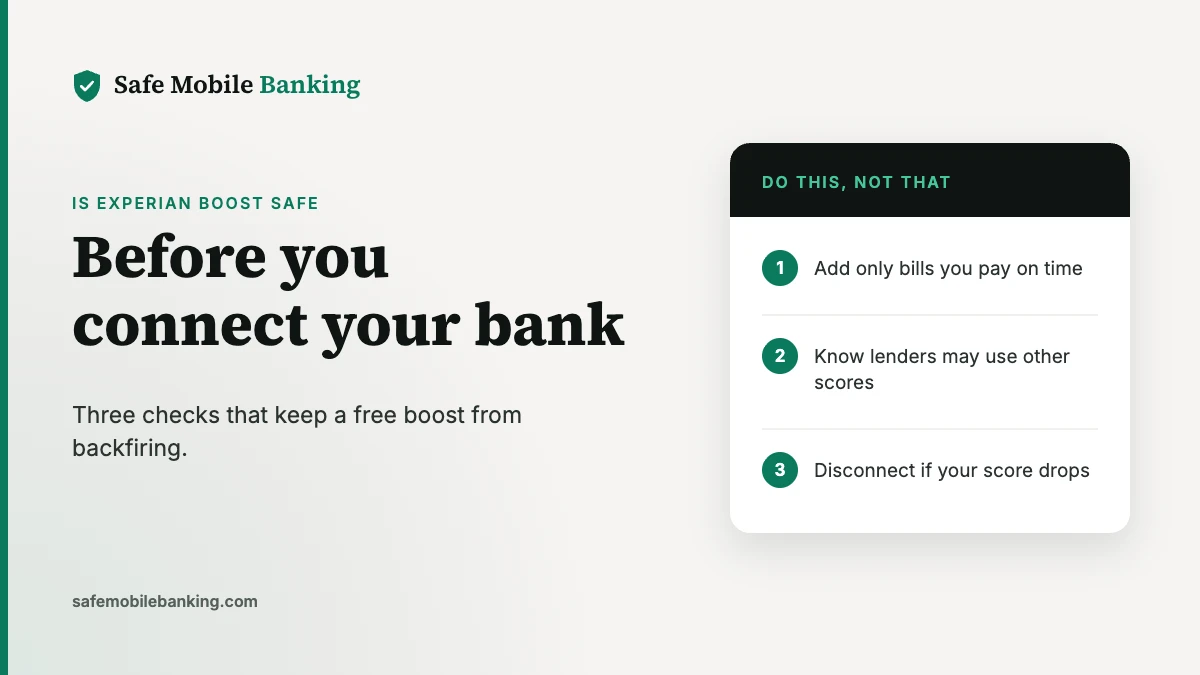
Is Experian Boost safe for you? 3 checks before you connect
- Add only bills you pay on time. Boost rewards a clean payment history.
- Know lenders may use other scores. Ask which bureau a lender checks before counting on the boost.
- Disconnect if your score drops. Experian says it should return to its previous result.
Building credit from scratch? See how Kikoff works and is Credit Karma safe.
Frequently asked questions
Is Experian Boost safe?
Yes. Experian Boost is a free feature from Experian, one of the three national credit bureaus. You connect the bank accounts you pay bills from, and Experian says it uses bank-level encryption. You can remove accounts at any time. It only changes your Experian credit file, not your Equifax or TransUnion files.
Does Experian Boost really work?
It can. Experian says most people who see an increase get an average of 13 points on their FICO Score 8 based on Experian data, but results vary and some scores stay the same or go down. Lenders that use Equifax, TransUnion or other score models won’t see the boost.
What bills count for Experian Boost?
Experian counts phone, utilities (electric, gas, water, trash), cable, satellite and internet, video streaming like Netflix, home, auto and life insurance, and rent paid online to select property managers or rent platforms. Health insurance and rent paid by check, cash or apps like Venmo or Zelle don’t count.
Can Experian Boost hurt your credit?
It can. Experian says some users’ scores may stay the same or drop. If your score goes down after you add accounts, you can remove them, and Experian says your score should return to its previous result.
Is Experian Boost free?
Yes. Experian says Boost is completely free. You only need a free Experian account to use it.
Sources
- Experian: Experian Boost (cost, eligible bills, 13-point average, FICO Score 8, removal; checked Nov 15, 2026)
- Consumer Financial Protection Bureau: Experian Information Solutions enforcement action (lawsuit status)
- Bloomberg Law: Experian sued by CFPB (Experian’s response)
- Consumer Financial Protection Bureau complaint database (company: Experian Information Solutions Inc.; Nov 15, 2025 to Nov 15, 2026)
- Experian on the Apple App Store
Safe Mobile Banking is a publisher, not a credit bureau or financial advisor. This article is general information, not financial advice. Experian and Experian Boost are trademarks of Experian; FICO is a trademark of Fair Isaac Corporation. We’re not affiliated with either. See our editorial standards.