Advertiser disclosure: Safe Mobile Banking may earn a commission if you open an account through links on this page. It never changes our Safety Score or what we say. How we make money.
How does Kikoff work? Kikoff sells a monthly plan, starting at $5 a month for 12 months, that opens a small credit account in your name and reports it to Equifax, Experian and TransUnion. You can’t spend that credit line at a store or withdraw it as cash. It only works in the Kikoff Store. What builds your credit is the account itself: an open credit line with on-time payments and almost no balance. Kikoff runs no credit check and charges no interest, and you can cancel anytime.
Last verified: November 14, 2026, against kikoff.com, kikoff.com/pricing, the Consumer Financial Protection Bureau complaint database and the Apple App Store.
See Kikoff’s current plans on kikoff.com (Basic starts at $5/mo. No credit check.)
Kikoff at a glance
| What | Fact | Source |
|---|---|---|
| Company | Kikoff Inc., NMLS ID 1930930 | kikoff.com footer |
| Main product | Credit Account (the “Kikoff tradeline”) | kikoff.com |
| Cheapest plan | Basic, $5/mo for 12 months ($60 total) | kikoff.com/pricing |
| Credit check | None | kikoff.com |
| Interest | None charged | kikoff.com |
| Reports to | Equifax, Experian and TransUnion | kikoff.com/pricing |
| Where the credit line works | Kikoff Store only | kikoff.com/pricing |
| Money-back window | 45 days from first purchase, once per person | kikoff.com/pricing |
| Consumer complaints (last 12 months) | 3,551 filed against Kikoff Inc. | CFPB database, pulled Nov 14, 2026 |
| App Store rating | 4.9 out of 5 (280K ratings) | Apple App Store, pulled Nov 14, 2026 |
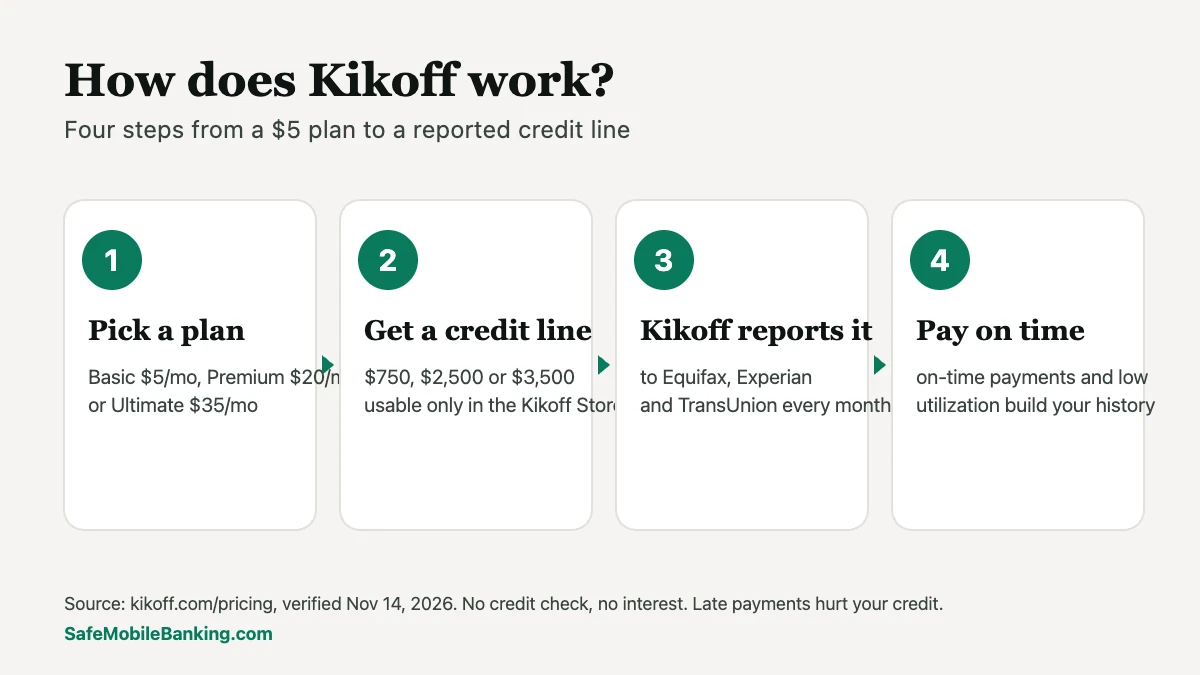
How does Kikoff work, step by step?
- Pick a plan. Basic is $5 a month, Premium is $20 a month and Ultimate is $35 a month. Approval depends on identity verification, not your credit score.
- Kikoff opens a credit account in your name. The account carries a reported limit of $750 on Basic, $2,500 on Premium or $3,500 on Ultimate.
- Kikoff reports the account every month. All three plans report the tradeline to Equifax, Experian and TransUnion.
- You pay the monthly plan fee on time. Each on-time payment adds to your payment history. Kikoff warns that late or missed payments hurt your credit.
- Your utilization stays low. Because the line can only be used in the Kikoff Store, most of the limit sits unused. A large unused limit lowers the share of available credit you’re using.
- The account ages. An open account that stays in good standing adds to the length of your credit history over time.
Kikoff plans and prices
| Plan | Price | Reported credit line | What it adds |
|---|---|---|---|
| Basic | $5/mo | $750 | Reports to all three bureaus, weekly credit report, rent reporting to Equifax and TransUnion |
| Premium | $20/mo | $2,500 | Everything in Basic plus three-bureau reports and scores, bill reporting, spending tracking |
| Ultimate | $35/mo | $3,500 | Everything in Premium plus $1M identity theft insurance and personal data protection |
Rent reporting can also add up to two years of past rent payments for a one-time $50 fee. Bill reporting covers phone, electricity, natural gas and water payments and goes to TransUnion.
What Kikoff is not
Three common assumptions are wrong, and each one matters before you sign up.
Is Kikoff a credit card?
No. The Kikoff Credit Account is a credit line, not a card you can use anywhere. Kikoff says its separate secured credit card is no longer offered.
Is Kikoff a credit builder loan?
No. Kikoff states its plan is not a credit builder loan. A credit builder loan holds borrowed money in a savings account and releases it when you finish paying. Kikoff doesn’t hold or release any money.
Does Kikoff give you money?
No. You can’t withdraw the credit line or move it to your bank account. It only covers purchases in the Kikoff Store. If you need cash, Kikoff is the wrong product.
Does Kikoff work?
It can, for the right person. Kikoff reports an average gain of 90 points (median 86) over one year for customers who started between 300 and 600, measured with Equifax VantageScore 3.0. Kikoff also says results aren’t guaranteed and may not be caused by Kikoff. Treat that number as the company’s own figure, not a promise.
Kikoff tends to help most when you have a thin credit file or no open revolving accounts, and you can make every payment on time. It helps least when your score is held down by collections, charge-offs or high balances on other cards. A new tradeline doesn’t erase those.
Is Kikoff safe and legit?
Kikoff is a real, licensed company: Kikoff Inc. holds NMLS ID 1930930. Its app is rated 4.9 out of 5 from about 280,000 ratings on the Apple App Store.
Complaints are the other side of the record. The Consumer Financial Protection Bureau logged 3,551 complaints against Kikoff Inc. in the 12 months ending November 14, 2026. Most were about credit reporting (1,901) and debt collection (1,324). A complaint is not proof of wrongdoing, and large companies collect more of them, but that volume is worth knowing before you hand over bank access. We cover the full record in our Kikoff review.
What Kikoff costs, start to finish
- Basic plan: $5 a month for 12 months, $60 in total.
- Interest: none.
- Optional rent backfill: $50 one time.
- Bank fees: Kikoff says your own bank may charge fees when Kikoff debits your account, and Kikoff isn’t responsible for them. Keep enough in your account on the payment date.
- Refund: full refund if you cancel within 45 days of your first purchase, once per person. No refund after you finish the plan.
How to cancel Kikoff
Kikoff says you can cancel anytime. To get your money back, cancel within 45 days of your first purchase. After that, cancelling stops future payments but doesn’t refund past ones. Closing an open credit line also removes its unused limit from your available credit, which can raise your utilization, so check where your score stands first.
Who Kikoff is for, and who should skip it
Good fit:
- You have no credit or a thin file and want a low-cost first tradeline.
- You can pay $5 a month without missing a payment.
- You don’t want a credit check or interest charges.
Skip it if:
- You need cash or a card you can spend anywhere.
- Your bank charges fees on automatic debits and your balance runs close to zero.
- Your score problem is old collections or high card balances. Fix those first.
Kikoff alternatives
If Kikoff isn’t the fit, compare it with Self (a credit builder loan that returns your savings at the end), Kovo and the Chime Credit Builder card. Our best credit builder apps page ranks them side by side by Safety Score.
Frequently asked questions
How does Kikoff work if I have no credit at all?
Kikoff runs no credit check, so a blank credit file doesn’t block you. The Kikoff tradeline can become one of the first accounts on your report, and each on-time payment starts your payment history.
How long does Kikoff take to build credit?
Kikoff’s own figure is measured over one year. The account has to report and age before it moves your score, so expect months, not days.
Does Kikoff report to all three credit bureaus?
Yes. Every plan reports the Kikoff tradeline to Equifax, Experian and TransUnion. Rent reporting goes to Equifax and TransUnion, and bill reporting goes to TransUnion.
Does Kikoff do a credit check?
No. Kikoff says it runs no credit check. Approval depends on identity verification.
What is a Kikoff tradeline?
It’s the Kikoff Credit Account as it appears on your credit report: an open credit line with a limit of $750, $2,500 or $3,500 depending on your plan.
Can a missed Kikoff payment hurt my credit?
Yes. Kikoff states that late or missed payments will negatively affect your credit.
Sources
- Kikoff home page and footer disclosures (verified Nov 14, 2026)
- Kikoff plans and pricing (verified Nov 14, 2026)
- Consumer Financial Protection Bureau Consumer Complaint Database, company “Kikoff Inc.”, complaints received Nov 14, 2025 to Nov 14, 2026 (pulled Nov 14, 2026)
- Apple App Store listing “Kikoff: Build Credit Quickly” (pulled Nov 14, 2026)
This article is general information, not financial advice. Safe Mobile Banking is not a lender or financial advisor.