Advertiser disclosure: Safe Mobile Banking may earn a commission from some companies we review. We don’t earn anything from Credit Karma, and commissions never change what we say. How we make money.
Short answer
Is Credit Karma safe? Yes. Credit Karma is owned by Intuit, and checking your own score there doesn’t hurt your credit. The thing to watch is the business model: it’s free because it earns money when you apply for the cards and loans it recommends, and the FTC ordered it in 2023 to stop false “pre-approved” claims.
- Free scores and reports; checking them is a soft inquiry
- Its recommendations are how it gets paid
- $3 million FTC order over “pre-approved” offers (2023)
Use Credit Karma the smart way (Free. Three habits that protect your credit.)
Last verified: November 15, 2026, against the Federal Trade Commission’s Credit Karma order, Consumer Reports, the Consumer Financial Protection Bureau complaint database and the Apple App Store.
Is Credit Karma safe? The short version
| Question | Answer | Source |
|---|---|---|
| Who owns it? | Intuit, the maker of TurboTax | Consumer Reports |
| Does checking my score hurt my credit? | No. Applying for a product it recommends usually does. | Credit Karma |
| Which scores does it show? | VantageScore 3.0 from TransUnion and Equifax, not FICO | Credit Karma |
| How does it make money? | From card and loan recommendations | Credit Karma |
| Regulatory record | $3 million FTC order over false “pre-approved” claims (final January 2023) | Federal Trade Commission |
| Complaints, last 12 months | 964 filed with the federal consumer bureau | CFPB database |
| App rating | 4.8 out of 5 from about 7.8 million ratings | Apple App Store |
Does Credit Karma hurt your credit score?
No. Looking at your own scores and reports on Credit Karma doesn’t lower your score. What can lower it is applying for a credit card or loan you find there, because the lender usually runs a hard inquiry. That’s the moment to slow down.
Credit Karma’s scores are VantageScore 3.0 scores based on TransUnion and Equifax data. Many lenders use FICO scores, so your Credit Karma number may not match what a lender sees.
What did the FTC find about Credit Karma?
The Federal Trade Commission alleged that from February 2018 to April 2021, Credit Karma told many consumers they were “pre-approved” for credit card offers, or had “90% odds” of approval, when they weren’t. For many of those offers, almost a third of consumers who applied were denied, and many took a hard inquiry on their credit. The FTC also said Credit Karma’s own testing showed “pre-approved” wording drew more clicks.
Credit Karma disputed the allegations but agreed to pay $3 million and stop the claims. The order became final in January 2023, and the FTC sent more than $2.5 million to affected consumers in October 2024.
Is Credit Karma safe for your data?
Credit Karma holds a lot of information about you, including your credit reports, and uses it to match you with offers. Protect the account like a bank login: a unique password and 2-step verification. If you use Credit Karma Money, those checking and savings accounts are provided through an FDIC-member partner bank, MVB Bank.
What do Credit Karma’s complaint records show?
The Consumer Financial Protection Bureau logged 964 complaints against Credit Karma, LLC from November 15, 2025 to November 15, 2026. The top issues:
- Managing an account: 328
- Incorrect information on a credit report: 85
- Closing an account: 75
- Improper use of a credit report: 71
- Unable to get a credit report or score: 46
Credit Karma closed 573 with an explanation, 244 with non-monetary relief and 133 with monetary relief; 14 were still in progress.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
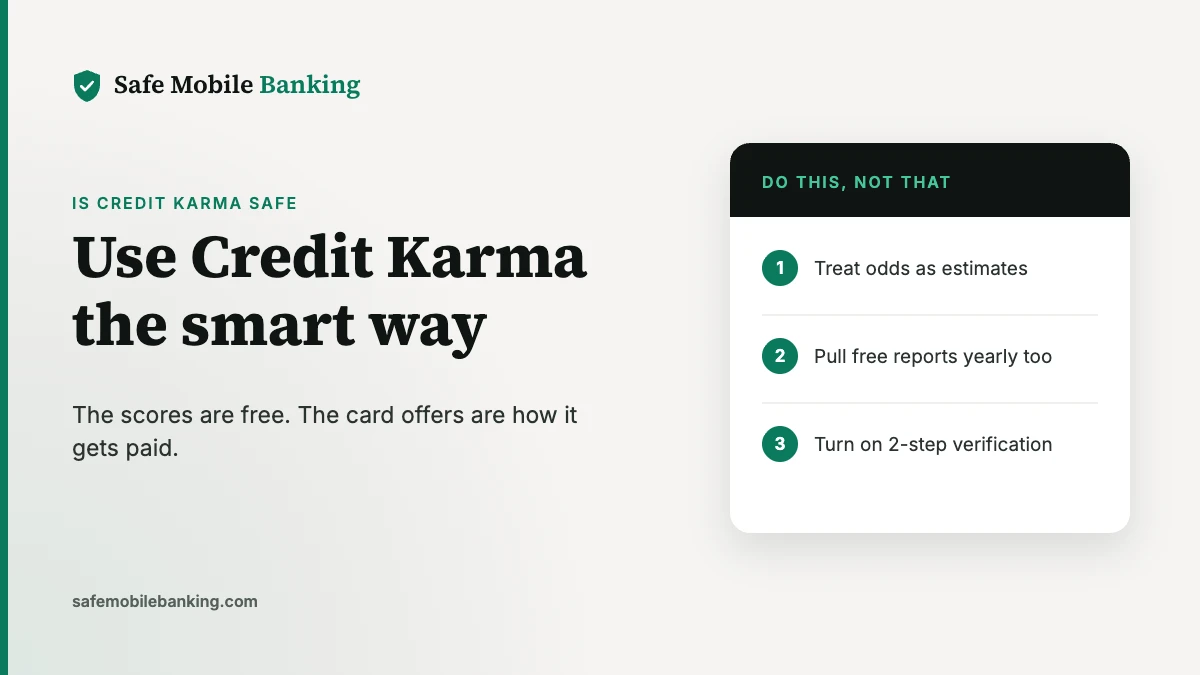
Is Credit Karma safe for you? 3 habits
- Treat approval odds as estimates. Only the lender decides, and each application can mean a hard inquiry.
- Pull your free reports from all three bureaus too. Credit Karma doesn’t show Experian. Get free reports at AnnualCreditReport.com, the official site.
- Turn on 2-step verification and use a unique password.
Want to raise your score rather than just watch it? A credit-builder product reports payments to the bureaus; see how Kikoff works and our Kikoff review. Credit Karma connects to other accounts too; see Is Plaid safe?
Frequently asked questions
Is Credit Karma safe to use?
Yes, for most people. Credit Karma is owned by Intuit, and checking your score there doesn’t hurt your credit. The catch is how it makes money: it recommends credit cards and loans. In 2023 the FTC finalized an order over its “pre-approved” claims.
Does checking Credit Karma hurt my credit score?
No. Viewing your own scores and reports on Credit Karma doesn’t lower your score. Applying for a card or loan you see there usually triggers a hard inquiry from the lender, which can.
Why is Credit Karma free?
Credit Karma earns money when members apply for and get financial products it recommends, such as credit cards and loans. That’s why its offers deserve the same skepticism as any ad.
Why is my Credit Karma score different from my bank’s score?
Credit Karma shows VantageScore 3.0 scores based on TransUnion and Equifax data. Many lenders use FICO scores, often with different data, so the numbers rarely match exactly.
What was the FTC case against Credit Karma?
The FTC alleged that from 2018 to 2021 Credit Karma told consumers they were pre-approved or had 90% odds for cards they often didn’t get. Credit Karma disputed the claims but agreed to pay $3 million and stop the claims; the order became final in January 2023.
Sources
- Federal Trade Commission: Credit Karma case (final order January 2023; refunds October 2024; checked Nov 15, 2026)
- Federal Trade Commission: Credit Karma complaint announcement (September 2022)
- Consumer Reports: Credit Karma told to halt pre-approved offers (Intuit ownership, MVB Bank)
- Consumer Financial Protection Bureau complaint database (company: Credit Karma, LLC; Nov 15, 2025 to Nov 15, 2026)
- Intuit Credit Karma on the Apple App Store
Safe Mobile Banking is a publisher, not a financial advisor. This article is general information, not financial advice. Credit Karma is a trademark of Credit Karma, LLC; we’re not affiliated with Credit Karma. See our editorial standards.