Advertiser disclosure: Safe Mobile Banking may earn a commission from some companies we review. We don’t earn anything from Klarna, and commissions never change what we say. How we make money.
Short answer
Is Klarna safe? Yes, as a company: Klarna is a large, licensed payments firm, and Pay in 4 charges no interest. The risk is the debt. Missed payments can bring late fees and collections, and several small plans at once can add up to a bill you can’t cover.
- 0% interest on Pay in 4 and a soft credit check to sign up
- Late fees, and collections if a balance goes unpaid
- 2,068 complaints to the federal consumer bureau in the last year
Use Klarna without the debt trap (Free. Three rules before your next checkout.)
Last verified: November 15, 2026, against Klarna’s U.S. customer service pages, the Consumer Financial Protection Bureau complaint database and the Apple App Store.
Is Klarna safe? The short version
| Question | Answer | Source |
|---|---|---|
| Who is Klarna? | A Swedish payments company, Klarna Bank AB, offering buy now, pay later in the U.S. | Klarna |
| Does Pay in 4 charge interest? | No. Longer Pay over time loans can. | Klarna |
| What if I pay late? | A late fee may be charged, and unpaid balances may go to collections | Klarna |
| Does it affect my credit? | Pay over time loans are reported to credit bureaus; collections can hurt your credit | Klarna |
| Complaints, last 12 months | 2,068 filed with the federal consumer bureau | CFPB database |
| App rating | 4.9 out of 5 from about 2.5 million ratings | Apple App Store |
How does Klarna work?
At checkout, Klarna lets you split a purchase. With Pay in 4, you pay a quarter up front and the rest in three more payments, with no interest. Klarna also offers longer Pay over time loans, which can carry interest. Payments come out automatically from the card or bank account you choose.
What happens if you miss a Klarna payment?
Klarna says a late fee may be charged per missed payment if it can’t collect after multiple attempts. Consumer finance reviews put the U.S. Pay in 4 late fee at up to $7, capped at 25% of the order; check your own order’s terms. If you stay behind, Klarna says the balance may be sent to collections, and you could be blocked from using Klarna.
The hidden cost: a failed automatic payment can also trigger an overdraft or returned-payment fee from your bank, on top of Klarna’s fee.
Does Klarna affect your credit score?
Signing up for Pay in 4 uses a soft credit check, which doesn’t affect your score. Klarna says it reports repayment activity for Pay over time loans to credit bureaus, so those payments can help or hurt. A balance sent to collections can damage your credit for years. If you want to build credit on purpose, a credit-builder product is designed for that; see how Kikoff works.
What do Klarna’s complaint records show?
The Consumer Financial Protection Bureau logged 2,068 complaints against Klarna AB from November 15, 2025 to November 15, 2026. The top issues:
- Problems making payments: 351
- Incorrect information on a credit report: 336
- Problems with a purchase shown on a statement: 283
- Attempts to collect a debt not owed: 223
- Problems with the company’s investigation of an issue: 110
Klarna closed 1,882 with an explanation, 167 with monetary relief and 2 with non-monetary relief; 16 were still in progress.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
Is that Klarna message a scam?
Scammers send fake “Klarna payment failed” texts and emails with links to a fake login page. Klarna payments and problems show up in the Klarna app. Open the app yourself instead of tapping a link, and see how to report a scam if you entered your details.
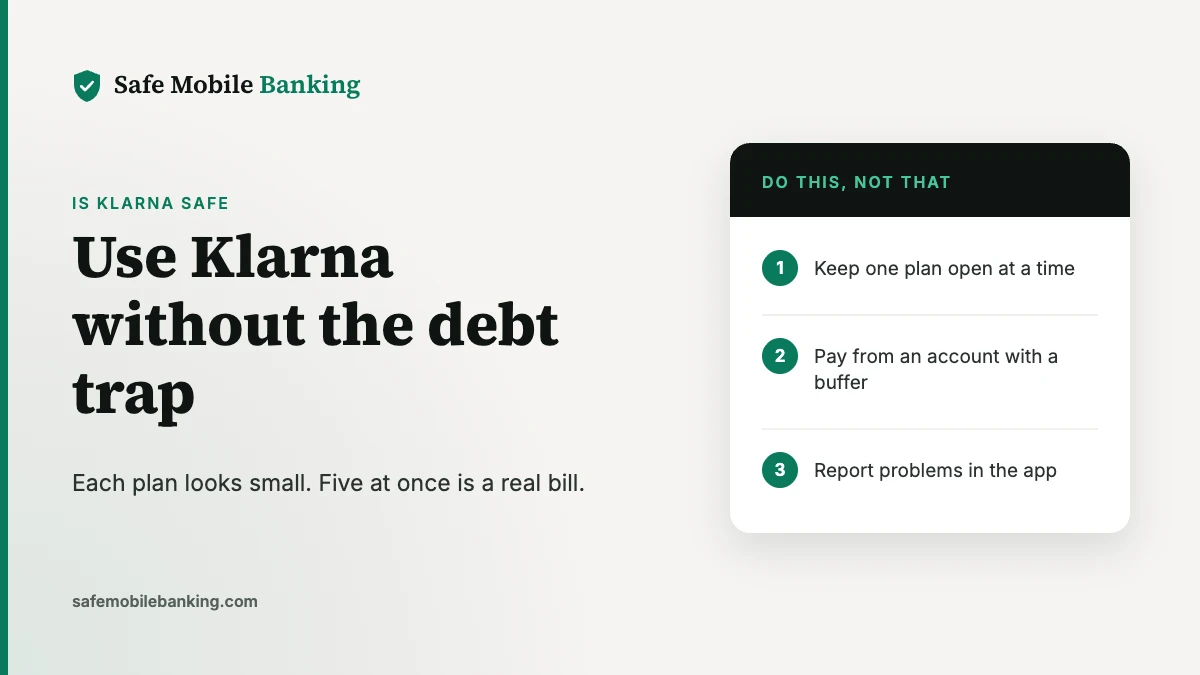
How to use Klarna safely: 3 rules
- Keep one plan open at a time. Stacking plans across Klarna, Afterpay and Affirm is how small purchases turn into missed payments.
- Pay from an account with a buffer, so a payment never bounces and triggers two fees.
- Report a problem with an order in the Klarna app before the next payment is due, instead of just stopping payment.
Is Klarna safe for you? Who should use it
A reasonable fit if you:
- Could pay for the purchase in full today.
- Want to spread one planned purchase over a few weeks at no interest.
- Keep track of every payment date.
Skip it if you:
- Already have other buy now, pay later plans open.
- Are using it to cover everyday expenses.
- Keep a thin balance in the account Klarna pulls from.
Frequently asked questions
Is Klarna safe to use?
Klarna is a large, licensed payments company, and Pay in 4 charges no interest. The real risks are late fees, collections if you fall behind, and stacking several plans at once. Use it for purchases you could pay for today.
Does Klarna hurt your credit score?
Signing up for Pay in 4 uses a soft credit check, which doesn’t affect your score. Klarna says it reports repayment activity for its Pay over time loans to credit bureaus, and an unpaid balance may be sent to collections, which can hurt your credit.
What happens if I miss a Klarna payment?
Klarna says a late fee may be charged if a payment can’t be collected after multiple attempts, and an outstanding balance may be sent to collections. You could also lose access to Klarna. Contact Klarna in the app before a due date if you can’t pay.
Is Klarna safe for my debit card?
Your card details are handled by Klarna’s payment system, but the bigger risk is a failed payment that triggers both a Klarna late fee and an overdraft fee from your bank. Pay from an account with a buffer.
What do people complain about with Klarna?
Over the last year, the most common complaints to the federal consumer bureau were problems making payments, incorrect information on credit reports, and charges for purchases. Klarna resolved 167 complaints with monetary relief in that period.
Sources
- Klarna: What happens if I can’t pay on time? (late fees, collections, credit reporting; checked Nov 15, 2026)
- MoneyLion: Klarna review (U.S. late fee amount and cap)
- Consumer Financial Protection Bureau complaint database (company: Klarna AB; Nov 15, 2025 to Nov 15, 2026)
- Klarna on the Apple App Store
Safe Mobile Banking is a publisher, not a lender or financial advisor. This article is general information, not financial advice. Klarna is a trademark of Klarna Bank AB; we’re not affiliated with Klarna. See our editorial standards.