Advertiser disclosure: Safe Mobile Banking may earn a commission from some companies we review. Commissions never change the Safe Mobile Banking Score or what we say. How we make money.
Short answer
Kikoff review verdict: Kikoff is legit. It’s a licensed lender that reports to all three credit bureaus, and it scores 8.0 out of 10 on the Safe Mobile Banking Score. It’s worth $5 a month if you have a thin credit file and will pay on time; it won’t fix collections or high card balances.
- Licensed lender, no credit check, no interest, all prices public
- Two-step login on every account, 4.9 stars from 280K App Store ratings
- 3,551 complaints filed with the federal consumer bureau in a year, mostly about credit reporting and debt collection
See if Kikoff is worth it for you (Four questions. Takes a minute.)
Last verified: November 14, 2026, against kikoff.com/pricing, Kikoff’s help center, state lender license records (Missouri, Indiana), the Consumer Financial Protection Bureau complaint database, the Apple App Store and Trustpilot.
Kikoff review: the verdict
Kikoff does what it says. For $5 a month, it opens a $750 credit line in your name and reports it to Equifax, Experian and TransUnion every month. You can only spend that line in the Kikoff Store, so most of it sits unused. That’s the point: an open account, paid on time, with almost no balance helps your payment history and your credit utilization.
It’s a good fit for someone with few or no open credit accounts. It’s a weak fit for someone whose score is held down by collections, charge-offs or maxed-out cards, because a new account doesn’t erase those. For the plan-by-plan mechanics, read how Kikoff works. This Kikoff review covers whether you can trust it and whether it’s worth paying for.
How Kikoff scored, test by test
| Test | Points | Why |
|---|---|---|
| Deposit and license protection | 3 / 3 | Missouri’s Division of Finance lists KikOff Lending, LLC as a consumer installment lender licensee, and Indiana’s regulator keeps an entity record for it. Kikoff doesn’t hold deposits for you; you pay a plan fee. |
| Fee transparency | 1.5 / 2 | All three plan prices, the 45-day refund window and the $50 rent backfill fee are on the public pricing page. The page states a 12-month term only for the $5 plan, not for Premium or Ultimate. |
| Regulatory record | 1 / 2 | We found no public enforcement action. But consumers filed 3,551 complaints in the last 12 months, with recurring themes of incorrect credit report information and debt collection. |
| Security features | 1.5 / 2 | Kikoff turned on two-step login for all accounts in June 2023 (code by text, or by email). It also pauses login after too many failed attempts. We couldn’t confirm transaction alerts or an account lock. |
| User ratings | 1 / 1 | 4.9 out of 5 from 280,000 ratings on the Apple App Store. |
Is Kikoff legitimate?
Yes. Kikoff is a real, licensed company. Its lending arm, KikOff Lending, LLC, is listed as a licensed consumer installment lender by Missouri’s Division of Finance, and the parent company lists NMLS ID 1930930 on its website. It reports to all three credit bureaus, runs no credit check to sign up and charges no interest on the Credit Account.
Legit doesn’t mean problem-free. The complaint record below is the part most reviews skip.
Kikoff bad reviews: what the complaints say
The Consumer Financial Protection Bureau logged 3,551 complaints against Kikoff Inc. from November 14, 2025 to November 14, 2026. The biggest themes:
- Incorrect information on a credit report: 1,262
- A collector took or threatened negative or legal action: 661
- Attempts to collect a debt the person says isn’t owed: 428
- Problems with the company’s investigation of a dispute: 360
Kikoff closed 3,532 of those complaints with an explanation and 19 with non-monetary relief. None were closed with money back. Complaint counts aren’t proof of wrongdoing, and a company with a large customer base will collect more of them. But a pattern of credit-reporting and collection disputes matters for a product whose whole job is your credit report.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
Trustpilot shows the same split. Kikoff has a 3.8 TrustScore from about 2,300 reviews: 77% are 5 stars and 14% are 1 star. The 1-star reviews mostly describe trouble cancelling, charges people didn’t expect, refunds they didn’t get, and accounts reported in a way they say hurt their credit.
Pros and cons
| Pros | Cons |
|---|---|
| Starts at $5 a month ($60 for 12 months) | The credit line only works in the Kikoff Store |
| Reports to Equifax, Experian and TransUnion | Heavy complaint volume about credit reporting and collections |
| No credit check, no interest | No refund after 45 days |
| Two-step login on every account | Your bank may charge you fees if a payment bounces |
| Cancel anytime | Won’t remove collections, charge-offs or late payments |
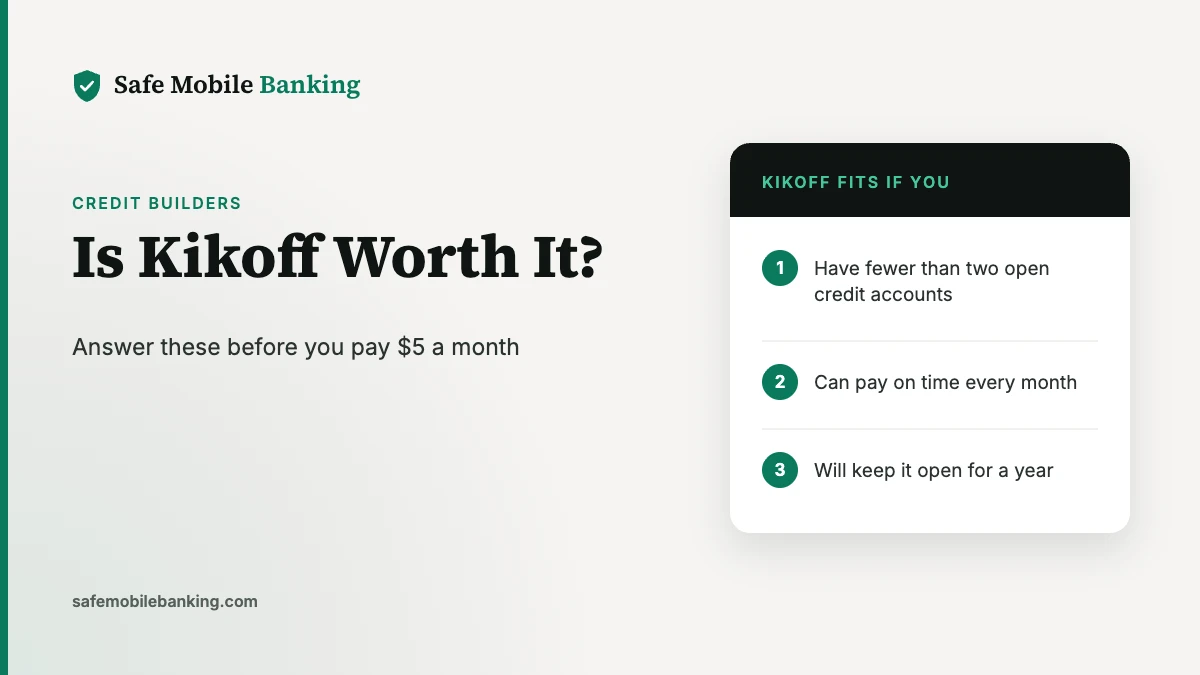
Is Kikoff worth it? Four questions
- Do you have fewer than two open credit accounts? If yes, a new reported account can add real weight to your file. If you already have several, the gain is smaller.
- Will $5 leave your bank account on time every month? A missed payment hurts the score you’re trying to build, and a bounced debit can trigger bank fees.
- Is your score held down by collections or high balances? If yes, pay those down first. Kikoff won’t outweigh them.
- Will you keep it open for at least a year? Payment history and account age build over time. Kikoff’s own figure (an average 90-point gain) covers only members who started with a score between 300 and 600 and kept the account open for a year with no missed payments, and Kikoff says results aren’t guaranteed.
If you answered yes, yes, no and yes, the $5 plan is a reasonable bet. Premium ($20 a month) and Ultimate ($35 a month) add bigger reported lines, bill reporting and identity theft insurance; pick them for those extras, not because a bigger line guarantees a bigger jump.
How to cancel Kikoff without hurting your credit
- Within 45 days: cancel for a full refund of your first purchase. Kikoff allows this once per person.
- After 45 days: cancelling stops future payments but doesn’t refund past ones.
- Before you close it: closing removes the unused limit from your available credit, which can push your utilization up. Check your other card balances first.
- Save proof: screenshot the cancellation confirmation. Several complaints describe charges after cancelling.
Frequently asked questions
Is Kikoff legit or a scam?
Kikoff is legit. It’s a licensed lender that reports to all three credit bureaus and scores 8.0 out of 10 on the Safe Mobile Banking Score. Its weak spot is customer complaints about credit reporting and collections.
Is Kikoff worth it?
For $5 a month, it’s worth it if you have a thin credit file and will pay on time for at least a year. It’s not worth it if collections or high balances are what’s holding your score down.
Does Kikoff hurt your credit?
Signing up doesn’t, because there’s no credit check. Missed payments will hurt it, and closing the account can raise your utilization.
Can you get money from Kikoff?
No. The credit line can’t be withdrawn as cash or moved to your bank. It only works in the Kikoff Store.
How long does Kikoff take to build credit?
Kikoff reports every month, but its own results figure measures members after a full year. Plan on 6 to 12 months of on-time payments before judging it.
Sources
- Kikoff: Pricing (plans, refund window, rent backfill fee, results footnote; checked Nov 14, 2026)
- Kikoff Help Center: Two-factor authentication
- Missouri Division of Finance: KikOff Lending, LLC license record
- Indiana Department of Financial Institutions: KikOff Lending, LLC
- Consumer Financial Protection Bureau complaint database (company: Kikoff Inc.; Nov 14, 2025 to Nov 14, 2026)
- Kikoff on the Apple App Store
- Kikoff on Trustpilot
Safe Mobile Banking is a publisher, not a financial advisor. This review is general information, not financial advice. See how we rate and our editorial standards.