Advertiser disclosure: Safe Mobile Banking may earn a commission from some companies we review. We don’t earn anything from MoneyLion, and commissions never change what we say. How we make money.
Short answer
Is MoneyLion legit? Yes, it’s a real company, and its spending account is held at Pathward, N.A., an FDIC-insured bank. But small advances can be expensive: optional Turbo fees and tips add up, a federal case over its memberships settled in 2025, and New York’s attorney general has sued over its advances.
- Instacash advances up to $500 with no interest and no credit check
- Optional Turbo fees and tips can make short advances costly
- $1.75 million CFPB settlement (2025); New York lawsuit filed in 2025
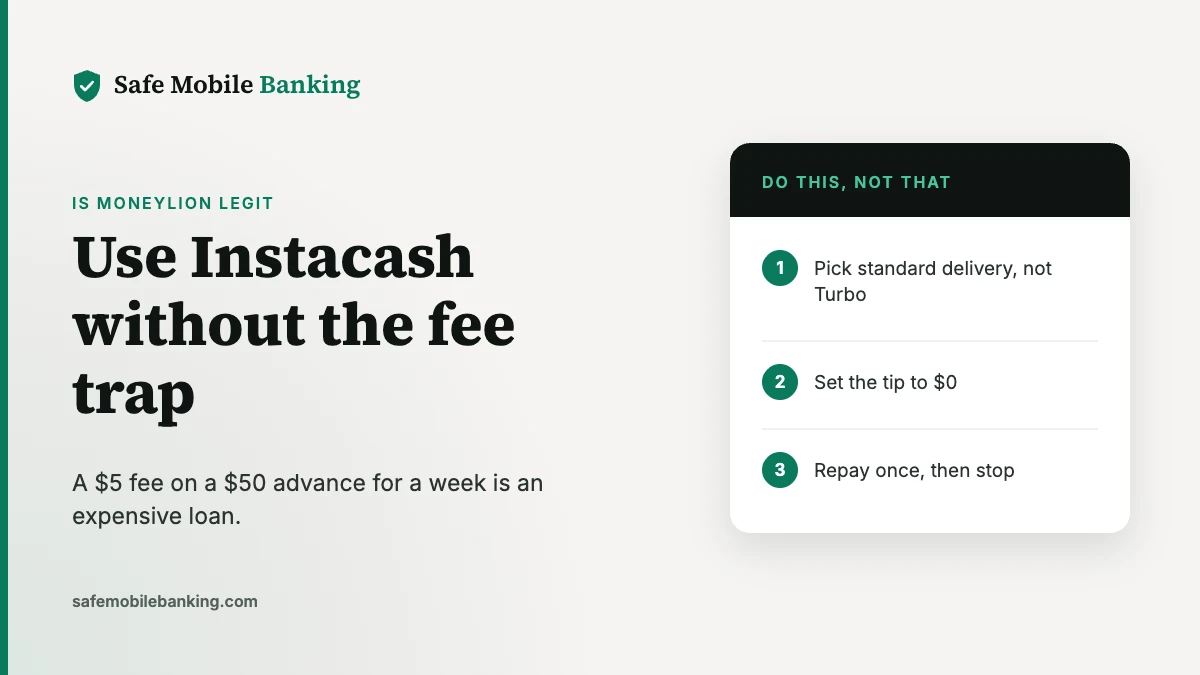
Use Instacash without the fee trap (Free. Three choices on the advance screen.)
Last verified: November 15, 2026, against MoneyLion’s Instacash page, the Consumer Financial Protection Bureau’s 2025 stipulated judgment, the New York Attorney General’s 2025 complaint, the CFPB complaint database and the Apple App Store.
Is MoneyLion legit? The short version
| Question | Answer | Source |
|---|---|---|
| Is MoneyLion a bank? | No. The MoneyLion Spend account is provided by Pathward, N.A., an FDIC-insured bank. | MoneyLion |
| How much is Instacash? | Up to $500 per advance; up to $1,000 with qualifying direct deposits to MoneyLion | MoneyLion |
| What does it cost? | No interest. Optional Turbo fee for instant delivery; optional tips. | MoneyLion |
| Federal case | CFPB settlement, November 2025: $1.75 million in redress; no admission of wrongdoing | CFPB |
| State case | New York Attorney General lawsuit over Instacash fees and tips, filed April 2025; allegations not proven in court | New York AG |
| Complaints, last 12 months | 1,092 filed with the federal consumer bureau | CFPB database |
| App rating | 4.8 out of 5 from about 332,000 ratings | Apple App Store |
How much does MoneyLion Instacash really cost?
MoneyLion says Instacash has no interest, no credit check and no mandatory fees. Standard delivery to a MoneyLion Spend account is free and takes 1 to 5 business days. Instant delivery carries an optional Turbo fee that varies with the advance amount and where the money goes, and the app asks for a tip.
Those charges are small in dollars and large as a share of the advance. In its lawsuit, New York’s attorney general alleges that MoneyLion’s Turbo fees ran up to $8.99 for an advance to an outside account, that a typical advance was $50 with a $4.99 fee and a $2 tip over about 10 days, and that fees and tips together amounted to annual rates above 500% on more than half of advances. MoneyLion hasn’t been found liable, and the allegations haven’t been proven in court.
The math is easy to check yourself: a $5 fee to borrow $50 for a week costs far more than a credit card or a credit union loan.
What did regulators allege about MoneyLion?
- Consumer Financial Protection Bureau, 2022 to 2025. The bureau sued MoneyLion in September 2022, alleging it charged servicemembers more than the Military Lending Act’s 36% rate cap by requiring paid memberships to get its loans, and didn’t let borrowers cancel memberships. In November 2025, a court entered a settlement requiring $1.75 million in consumer redress. MoneyLion can no longer block cancellations over unpaid balances or report negative credit information over unpaid membership fees. MoneyLion didn’t admit or deny wrongdoing.
- New York Attorney General, April 2025. New York sued MoneyLion, alleging that Instacash advances are high-cost payday loans that violate the state’s usury limits, and that the app pushes users toward fees and tips. The case seeks restitution and penalties. The allegations haven’t been proven in court.
What do MoneyLion’s complaint records show?
The Consumer Financial Protection Bureau logged 1,092 complaints against MoneyLion Inc. from November 15, 2025 to November 15, 2026. The top issues:
- Incorrect information on a credit report: 226
- Managing an account: 118
- Took or threatened to take negative or legal action: 108
- Attempts to collect a debt not owed: 66
- Problems with the company’s investigation of an issue: 62
MoneyLion closed 1,083 with an explanation, 6 with monetary relief and 2 with non-monetary relief; 1 was still in progress.
Complaints are consumers’ claims as logged by the Consumer Financial Protection Bureau. The bureau doesn’t verify them, and a complaint isn’t proof of wrongdoing.
Is MoneyLion legit for you? 3 ways to avoid the fees
- Choose standard delivery. It’s free to a MoneyLion Spend account; Turbo is the fee.
- Set the tip to $0. MoneyLion says tips are optional.
- Use it once, then stop. Repeat advances are how small fees turn into a cycle. If you’re short every month, a credit union small-dollar loan is usually cheaper.
MoneyLion connects to your bank to check your deposits; see Is Plaid safe? for how those links work. Comparing apps? See our Albert review.
Who should use MoneyLion, and who should skip it?
It can work if you:
- Need a small, one-time advance and can wait for free delivery.
- Will skip tips and Turbo fees.
- Have steady direct deposits to repay on schedule.
Skip it if you:
- Expect to need an advance every pay period.
- Are an active-duty servicemember; check the full cost against the Military Lending Act’s 36% cap.
- Would keep a paid membership you don’t use.
Frequently asked questions
Is MoneyLion a legit company?
Yes. MoneyLion is a real financial technology company, and its MoneyLion Spend account is provided by Pathward, N.A., an FDIC-insured bank. MoneyLion itself isn’t a bank. It has faced a federal settlement and a New York lawsuit over its fees, so read the costs carefully.
Does MoneyLion Instacash charge interest?
MoneyLion says Instacash has no interest and no mandatory fees. Instant delivery carries an optional Turbo fee that varies by amount, and the app asks for tips. New York’s attorney general alleges those fees and tips work out to triple-digit annual rates on short advances; MoneyLion hasn’t been found liable.
How much can I get from MoneyLion Instacash?
MoneyLion says up to $500 per advance, and up to $1,000 if you have qualifying recurring direct deposits into a MoneyLion Spend account. Your limit depends on your deposits and account history.
What was the CFPB case against MoneyLion about?
The Consumer Financial Protection Bureau sued in 2022, alleging MoneyLion charged servicemembers more than the Military Lending Act’s 36% cap by requiring membership fees, and didn’t let borrowers cancel memberships. A court entered a settlement in November 2025 with $1.75 million in redress; MoneyLion didn’t admit or deny wrongdoing.
Can I cancel a MoneyLion membership?
Yes. Under the 2025 settlement, MoneyLion can’t block borrowers from canceling memberships because of unpaid loan balances or membership fees. If you have trouble, file a complaint with the Consumer Financial Protection Bureau.
Sources
- MoneyLion: Instacash (limits, Turbo fees, Pathward; checked Nov 15, 2026)
- CFPB v. MoneyLion: stipulated final judgment (November 2025)
- Banking Dive via Yahoo Finance: MoneyLion to pay $1.75 million to settle CFPB lawsuit
- New York Attorney General: Lawsuit against MoneyLion and DailyPay (April 2025)
- State of New York v. MoneyLion: complaint
- Consumer Financial Protection Bureau complaint database (company: MoneyLion Inc.; Nov 15, 2025 to Nov 15, 2026)
- MoneyLion on the Apple App Store
Safe Mobile Banking is a publisher, not a lender or financial advisor. This article is general information, not financial or legal advice. MoneyLion is a trademark of MoneyLion Technologies Inc.; we’re not affiliated with MoneyLion. See our editorial standards.